Importing a car from Denmark into Germany: check the Bilbogen and original documents, agree the export price, and prepare transport, inspections and taxes.
Before paying, check the seller, vehicle identity, original documents, Bilbogen and condition. Separate the final price from any potential tax refund, prepare deregistration and insured transport, and clarify German inspection evidence, taxes and registration.
This guidance is for private buyers resident in Germany purchasing ordinary passenger cars already registered in Denmark. The location in an advert alone does not prove registration. Greenland, the Faroe Islands and atypical cases involving non-EU countries are excluded. No customs duty applies to an ordinary purchase within the European Union (EU). 11 For other countries of origin, see the guide for buyers in Germany (in German).
Check the seller, Bilbogen and original documents before a deposit
Match the vehicle identification number (VIN), known as stelnummer in Danish, on the car against the contract and documents. The Registreringsattest, the Danish registration certificate, consists of Parts I and II. It names the primary owner and user; additional owners or users may not appear. Being registered as a user does not prove authority to sell. Ask for a clear explanation of any representation, company sale, joint ownership or finance arrangement. 1
Search the Bilbogen, the official register of security rights over vehicles, using the exact VIN. Entries include mortgages, retention of title and attachments. The register records neither ownership nor all the seller’s personal debts. For relevant entries, obtain documented release before payment and check the current register entry again. 2 20
Have missing originals obtained in advance: the primary owner can order replacements through the Motor Register; other applicants need the separate procedure for submitting evidence. A paid copy contains only Part I: it may replace that part when driving abroad, but is insufficient for an ownership transfer or re-registration. A temporary certificate for driving abroad requires the ordinary certificate to have already been ordered and to be unavailable in time. Neither replaces a complete set of originals for the sale. 1
Record defects, mileage assurances, originals, keys and payment terms; clarify seller status, invoice type and the law governing the contract. Residence in Germany does not automatically make all German statutory warranty rules apply. Postpone payment if identity, encumbrances, missing essential originals or serious technical findings remain unresolved.
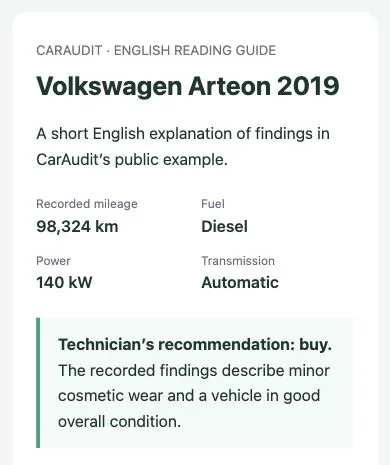
Editorial English reading guide: Volkswagen Arteon 2019, 98,324 km, 140 kW, diesel, automatic.
Editorial English reading guide to the public example. Original: English navigation and Spanish technician notes; not the reader’s vehicle.
Compare syn records with the car’s current condition
Use the official service to search for available syn reports, the Danish technical inspection reports, by registration number or VIN. They contain vehicle identity, inspection date, result and, where available, the odometer reading. Put these readings in chronological order alongside service invoices. Missing reports and earlier periods abroad remain gaps; a plausible sequence does not prove a complete history. 24 3 When considering competing Finnish offers, compare original documents and history records using the guide to buying a car in Finland (in German).
Check for signs of repairs and corrosion, and inspect the underbody, brakes, tyres, suspension and drivetrain. Arrange a cold start, diagnostics and a lawful test drive. Paint readings need to be interpreted in the context of the panel; fault codes do not replace a repair quote, and an empty fault memory does not prove that the car is free of defects. Tax valuation, roadworthiness inspection and a pre-purchase inspection answer different questions. 18
| Finding | Decision before payment |
|---|---|
| Inconsistent VIN or authority to sell | Clarify the seller’s position and original evidence; postpone payment. |
| A right is registered in the Bilbogen | Request documented release and the current register entry. |
| Gaps in the syn/service records | Investigate missing periods and the car’s current condition specifically. |
| The price depends on a refund | Record the recipient, applicant and rejection risk in the contract. |
Export price and an optional registration tax refund
Any potential refund concerns Danish registration tax, not value added tax (VAT). Record the final price and currency, applicant, economic recipient and the risk of a reduced or refused refund in writing. A contract does not bind Motorstyrelsen, the Danish Motor Vehicle Agency. An expected refund is not secured funding for the purchase. Binding advance rulings require a separate application. 4
Only when applying for a refund: the extended registration and customs inspection must be no more than four weeks old when the valuation application is made. There is also an application fee of 2,250 Danish kroner (DKK), the plates must be returned, and evidence of ownership, sale where applicable, and export must be provided. An applicant who is not the registered owner must prove ownership. Motorstyrelsen may require its own physical inspection; coordinate this before transport. 4
The car must actually leave Denmark no later than three months after the refund application. This is not automatically a three-month deadline for submitting every document. Submit evidence promptly and observe any separate authority deadlines. A later export requires a new application and another inspection recent enough to qualify. 23
Evidence of export can include foreign registration, a CMR consignment note for international road freight, or an export declaration. A signed export/receipt declaration, including one you draw up yourself, is supplementary evidence only. Agree who obtains and forwards the evidence. 4 25
The calculation starts with the registration tax payable on an equivalent import, less 15 %, with a minimum deduction of 8,500 DKK for a passenger car; the refund is capped at the tax originally paid. The deduction is not a general export fee. Payment goes to the applicant’s NemKonto, the account registered with the authorities for receiving payments; public debts may first be offset. An encumbrance registered in the Bilbogen when the application is made leads to rejection, with the application fee returned when rejection is on that ground. 4 25
Exclusions include vehicles that have lost their tax identity following alterations, accident-damaged vehicles outside the specified tax-free rebuilding rules, vehicles more than 35 years from first registration, and vehicles that cannot be registered or pass inspection. Equipment fitted later without registration tax having been paid on it does not qualify for a refund. Check these conditions before calculating any price. 25
Arrange deregistration and lawful transport
To deregister the car, hand the plates to a number plate operator: the operator sets its own fee and the insurer is notified automatically. Keep the deregistration receipt and evidence of status. You cannot drive home on plates that have been returned, and the seller’s policy is no substitute for an agreed transport arrangement. German registration does not automatically complete Danish deregistration. 7 14
| Transport method | Requirements |
|---|---|
| Driving with prøvemærker, temporary number plate stickers | 100 DKK per calendar day, 00:00–23:59, including liability insurance; no more than seven days, named driver only. |
| From Denmark to or through Germany | This direction is confirmed; the reverse is not. Check recognition in any additional countries; confirm insurance for the entire route and dates, documents and roadworthiness. |
| Carried on a transporter or trailer | Choose this if lawful driving or roadworthiness is unresolved; agree a specific quote and evidence of export. |
A foreign applicant without a Danish personal identification number (CPR) is assigned an entry in the Alternative Contact Register (AKR). If you do not have MitID, Denmark’s digital identity, the official English instructions provide a contact route without logging in. Prepare driver identification and proof of payment, and arrange approval and collection before travelling. 6 5
Record the handover date, odometer reading, keys, originals and any discrepancies in writing; coordinate the balance payment with handover. When considering Swedish alternatives, also compare the work involved in collection and transport using the guide to buying a car in Sweden (in German).
German registration, roadworthiness inspection (HU) and VAT
Before buying, agree the documents with your registration authority: identification, purchase contract/invoice, foreign originals and existing plates, electronic insurance confirmation (eVB), technical data and inspection evidence. You need a SEPA direct debit mandate for motor vehicle tax; SEPA means Single Euro Payments Area. 12
For a vehicle with type approval, an EU Certificate of Conformity (CoC) or manufacturer’s data confirmation may be used. A missing CoC alone does not make an expert report under § 21 of the German Road Traffic Licensing Regulations (StVZO) mandatory; without type approval, that expert-report procedure is required. Berlin serves as a local example. If Part II of a foreign two-part certificate is missing, § 8 requires confirmation from the foreign authority via the Federal Motor Transport Authority (KBA). 14 13
When is the Danish inspection report sufficient?
For an EU-type-approved vehicle previously used in the European Union or European Economic Area (EU/EEA), § 8 of the German Vehicle Registration Regulation (FZV) requires an inspection under § 29 of the German Road Traffic Licensing Regulations (StVZO) before registration if it would be due under German intervals. A documented inspection report from the previous EU/EEA state of use that meets Directive 2014/45/EU may replace that inspection. The next due date follows German intervals: for ordinary privately used passenger cars, the first inspection is after 36 months, then every 24 months; special uses may differ. If evidence of first use is missing, the German § 29 inspection is required. Vehicles previously used outside the EU/EEA are subject to a separate mandatory § 29 inspection rule. 13 21
When do German VAT obligations arise?
At acquisition, a car is new for tax purposes if it has travelled no more than 6,000 km or its first use was no more than six months ago. First registration is not an automatic substitute for first use. It is used only once both thresholds have been exceeded. For a private acquisition of an EU vehicle that is new for tax purposes, Germany charges 19 % on the statutory taxable amount. 9 10 11
No VAT is charged on a private sale of a vehicle that is used for tax purposes. With a dealer, distinguish ordinary VAT treatment from the margin scheme. The absence of a separate VAT line alone does not establish a particular invoice type; crossing the border creates neither automatic German acquisition VAT nor an automatic purchase net of VAT. 11 26
For individual vehicle taxation, § 18 paragraph 5a of the German VAT Act (UStG) requires a self-assessed return to be filed and payment to be made no later than the tenth day after the day the tax arose. You must personally sign a paper return. Before buying, clarify when the tax arises and how to file with the tax office, independently of the registration date. 22
Complete the budget before booking your trip
Keep currencies separate and include only the chosen transport method and applicable additional items. Obtain missing amounts; they are not zero. There is no complete total without all the quotes. Budget for annual insurance and motor vehicle tax separately from one-off import costs; the tax depends on factors including engine capacity, CO₂, drivetrain and first registration. 15 For competing Austrian offers, the guide to buying a car in Austria (in German) helps you compare documents and transport arrangements.
| Item | Amount | Condition / how to obtain it |
|---|---|---|
| Purchase price and invoice | To be determined | To be determined: agree the contractual final price and currency, seller status and invoice type; do not deduct an expected refund. |
| German basic registration fee | 30.00 EUR | German Road Traffic Fees Schedule (GebOSt) 221.1: basic fee; plates, documents and applicable surcharges are extra. |
| Optional refund application | 2,250.00 DKK | Applies only to a refund application; agree who pays. It is not a general export fee. |
| Prøvemærker per calendar day | 100.00 DKK | Per calendar day including liability insurance; only for the chosen lawful drive, no more than seven days. |
| Driving or transport with the car carried as a load | To be determined | To be determined: obtain route, travel, ferry and insurance costs or a quote for carrying the car; these are alternatives. |
| VAT: only a car that is new for tax purposes | To be determined | To be determined: 19 % of the statutory taxable amount only for a vehicle that is new for tax purposes; clarify the amount with the tax office. |
| Inspection, CoC/expert report, modifications | To be determined | To be determined: clarify the vehicle documents and required inspections/modifications with the inspection body. |
| Plates, documents, additional items | To be determined | To be determined: ask the plate supplier and registration authority; not included in the basic fee. |
| Annual motor vehicle tax | To be determined | To be determined: use the vehicle data to calculate the tax; annual cost, insurance separate. |
| Data retrieval surcharge | 15.30 EUR | Only if KBA data cannot be retrieved AND the data are also absent from the local register. |
| Choice of registration number | 10.20 EUR | Only for a number outside the regular allocation. |
| Exchange of the Fahrzeugbrief document | 5.10 EUR | Only for exchanging a Fahrzeugbrief, the former German vehicle registration document, for registration certificate Part II. |
| Interchangeable registration plates | 6.00 EUR | Only when interchangeable registration plates are allocated. |
| Danish deregistration | To be determined | To be determined: ask the number plate operator for the fee and agree who pays. |
| Extended inspection for a refund application | To be determined | To be determined: refund application only; ask the syn inspection centre for its price, in addition to the application fee. |
| Individual CarAudit quote | To be determined | To be determined: enquire individually about scope, price and timing at the exact Danish location. |
| Ongoing insurance | To be determined | To be determined: give the insurer the vehicle, user and policy details; recurring annual cost. |
| Repairs and maintenance | To be determined | To be determined: obtain workshop quotes based on specific findings. |
Sources: 8 4 5 7 9 10 11 12 13 14 15 16 17 18
Four decisions before payment and collection
Clarify these four stages before payment and collection; the details are in the relevant sections.
| Four decisions before payment and collection | Progress |
|---|---|
| Before paying, cross-check the VIN, authority to sell, Bilbogen and both original documents. | Open |
| Compare syn and service records and establish the current condition on site. | Open |
| Firmly agree the final price, any potential refund, deregistration and insured transport. | Open |
| Prepare the CoC, HU evidence, eVB, tax and registration documents for Germany. | Open |
Some evidence is still missing. Use the next steps listed.
Frequently asked questions
Am I automatically entitled to the Danish export refund?
No. The registration tax refund depends on the authority’s conditions and is not an automatic buyer’s discount. Agree the final price, applicant, economic recipient and rejection risk in the contract. 4
What does the Bilbogen tell me about the car?
It shows security rights over the vehicle against its VIN: mortgages, retention of title or attachments, neither ownership nor all the seller’s debts. Before paying, obtain documented release of relevant rights and recheck the current entry. 2 20
Is a copy of the Registreringsattest enough?
The paid Part I copy cannot be used for ownership transfer or re-registration, but may replace Part I when driving abroad. Obtain complete originals or replacements agreed with the authorities for the sale and registration. The temporary certificate for driving abroad requires an ordinary certificate that has already been ordered but is unavailable in time. 1
Can I drive to Germany after returning the plates?
Not on plates that have been returned. Arrange permitted prøvemærker for travel from Denmark to/through Germany, or transport with the car carried as a load, beforehand. If driving, confirm driver authorisation, validity dates, documents, roadworthiness and insurance for the entire route. 7 5 6
Do I need a new German roadworthiness inspection (HU)?
For an EU-type-approved vehicle previously used in the European Union or European Economic Area (EU/EEA), § 8 of the German Vehicle Registration Regulation (FZV) requires an inspection under § 29 of the German Road Traffic Licensing Regulations (StVZO) before registration if it would be due under German intervals. A documented inspection report from the previous EU/EEA state of use that meets Directive 2014/45/EU may replace that inspection. The next due date follows German intervals: for ordinary privately used passenger cars, the first inspection is after 36 months, then every 24 months; special uses may differ. If evidence of first use is missing, the German § 29 inspection is required. Vehicles previously used outside the EU/EEA are subject to a separate mandatory § 29 inspection rule. 13 21
When is the car new for VAT purposes?
At acquisition, no more than 6,000 km OR no more than six months since first use is enough. Used status requires both thresholds to be exceeded. For privately acquired EU vehicles that are new for tax purposes: 19 % in Germany, plus filing and payment by the tenth day after the day the tax arose; clarify this with the tax office independently of registration. 9 10 22
Which deadlines apply only to the refund application?
Extended inspection: no more than four weeks old when the valuation application is made. Actual export: no later than three months afterwards. The latter is not automatically a deadline for submitting documents. Submit evidence promptly and observe separate authority deadlines. 4 23
How do I enquire about a CarAudit inspection in Denmark?
Use the German contact page and provide the advert, VIN, location and seller’s contact details: Denmark is absent from the standard country selection. Obtain individual confirmation of inspection availability, scope, price and timing. An enquiry is not a booking. 16 17
Sources
- Motorstyrelsen — Registreringsattest
- Danish Court Administration — Motor Vehicle Securities Register
- Færdselsstyrelsen — Synsrapporten
- Motorstyrelsen — Exporting vehicles
- Motorstyrelsen — Prøvemærker
- Motorstyrelsen — Temporary stickers
- Motorstyrelsen — Deregister vehicle and return plates
- GebOSt Anlage — Gebührennummer 221
- UStG § 1b — innergemeinschaftlicher Erwerb neuer Fahrzeuge
- UStG § 12 — Steuersätze
- Your Europe — VAT when buying or selling a car abroad
- Bundesportal — Zulassung eines gebrauchten Kraftfahrzeuges aus einem EU-
- FZV § 8 — Zulassung nach vorheriger Zulassung in einem anderen Staat
- Berlin — EU/EEA used vehicle registration
- Zoll — Übersicht zur Kraftfahrzeugsteuer
- CarAudit Deutschland — contact for individual enquiry
- CarAudit German order form — complete country list, noDenmark
- CarAudit Deutschland — Was wir prüfen
- Carvago global vehicle selection directory
- Borger/Tinglysningsretten — Bilbogen enquiry
- StVZO Anlage VIII
- UStG18(5a) — individual vehicle taxation
- Motorstyrelsen — Actual export deadline clarification
- Borger/Færdselsstyrelsen — Search inspection reports
- Motorstyrelsen — Eksport af bil eller MC
- UStG § 25a — Differenzbesteuerung